5.7 Foreclosure
Foreclosure
Foreclosure is the legal process by which a lienholder enforces a lien by forcing the sale or transfer of the secured property. State law governs the process, which may be judicial, non-judicial, or strict foreclosure.
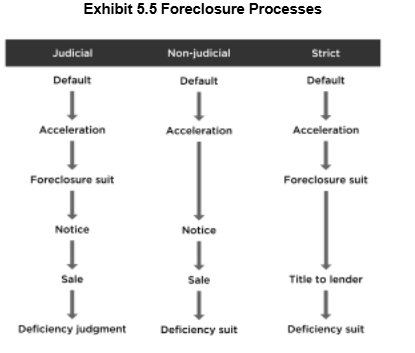
- Judicial foreclosure: Requires a court proceeding. The lender accelerates the debt, files a foreclosure suit, and the court orders a public sale. Proceeds pay liens by priority, and deficiency judgments may be issued for remaining debt. Borrowers may have a right of redemption.
- Non-judicial foreclosure: Used when the mortgage has a “power of sale” clause. The lender gives notice and sells the property without court action. No right of redemption, but the lender may file a separate deficiency suit.
- Strict foreclosure: The lender files suit, and if the borrower does not pay within a court-set period, the court awards title directly to the lender.
- Deed in lieu of foreclosure: The borrower voluntarily deeds the property to the lender to avoid foreclosure proceedings. Existing liens remain on the property.
- Short sale: The lender agrees to accept a sale price lower than the loan balance, often releasing the seller from further obligation. The process requires lender approval and may have tax consequences.
Topic 5.7 Check-In
When Payments Stop
Choose the best answer for each question, then select Check Answers.
Which foreclosure process allows the lender to sell the property without going to court?
Non-judicial foreclosure is possible when the mortgage has a “power of sale” clause.
What is a deficiency judgment?
If the sale does not cover the debt, the lender may seek a deficiency judgment.
🔒 Mark Complete unlocks when every answer is correct.