21.7 TILA/RESPA Integrated Disclosure Rule
Under the TILA/RESPA Integrated Disclosures (TRID) rule (effective October 3, 2015), lenders must use
the Closing Disclosure (H-25) to disclose settlement costs to the consumer. This form shows the costs the buyer
will pay at closing—whether paid to the lender or to other parties.
Timing matters: the consumer must receive the completed Closing Disclosure no later than three business days before
consummation of the loan, and has the right to inspect a revised form one business day before closing.
Page 1: Big picture totals + key loan terms
Page 1 contains four main sections: General Information, Loan Terms, Projected Payments,
and Costs at Closing.
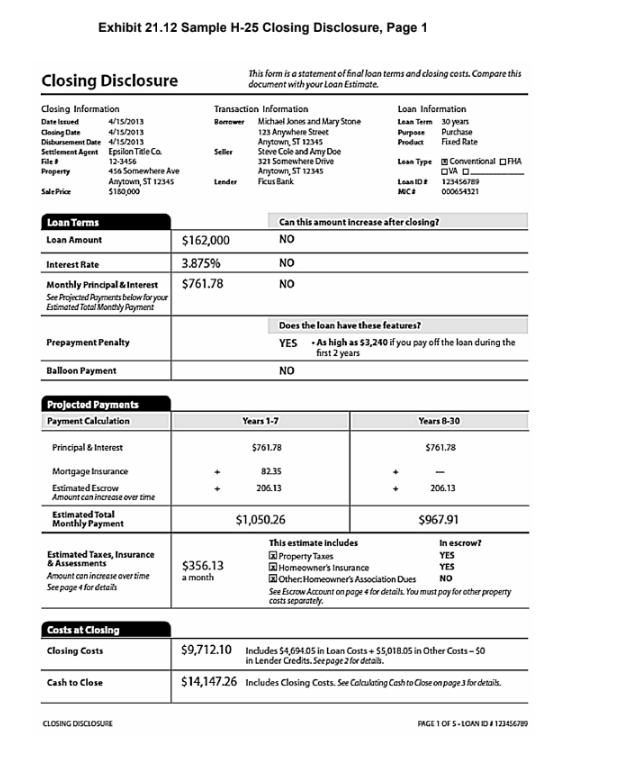
Focus on what each section is for (not memorizing every line).
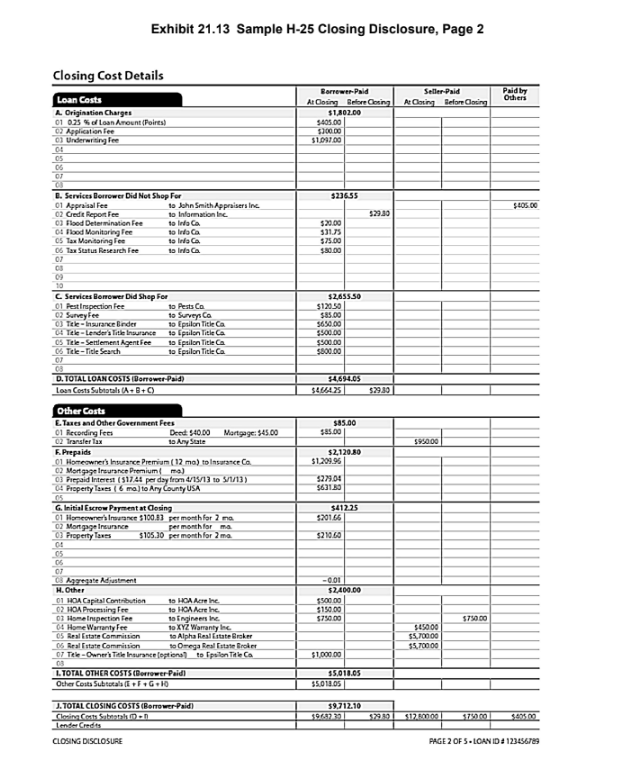
Page 2: Itemized closing costs
Page 2 breaks closing costs into Loan Costs and Other Costs, and shows who pays them:
borrower (at/before closing), seller (at/before closing), or others.
- Loan Costs: origination charges, required services not shopped for, services shopped for, totals.
- Other Costs: taxes/government fees, prepaid items, initial escrow payment, and other items (including commissions and prorations).
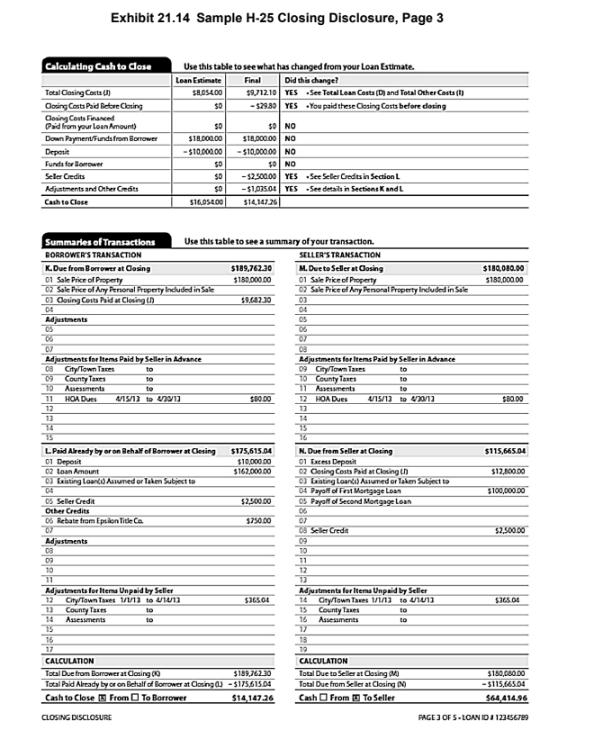
Page 3: Cash to close + summaries of transactions
Page 3 shows how the final numbers compare to the Loan Estimate and calculates the buyer’s Cash to Close.
It also summarizes the borrower’s and seller’s transactions (amounts due, amounts already paid, adjustments, and the final cash figure).
Page 4: Additional loan disclosures
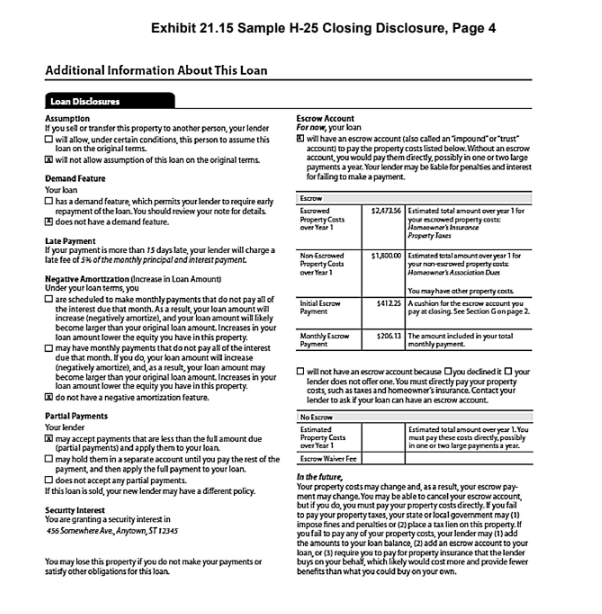
Page 4 covers disclosures like assumption, demand feature, late payment, negative amortization, partial payments, security interest,
and escrow account details.
Page 5: Loan calculations + other disclosures + contacts
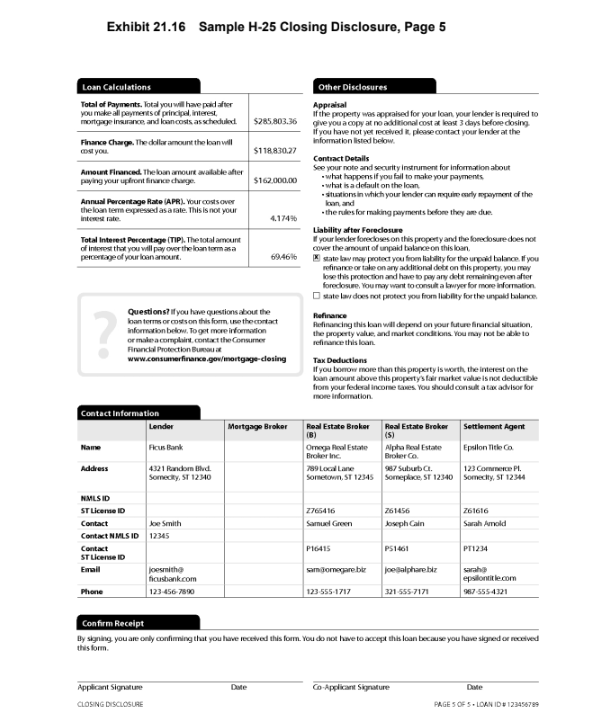
Page 5 includes loan calculations (total payments, finance charge, amount financed, APR, TIP), other disclosures (like appraisal copy and liability),
contact information for parties involved, and a confirm-receipt signature area.
Know Before You Owe
Choose the best answer for each question, then select Check Answers.
Under TRID, the form used to disclose settlement costs to the consumer is the:
TRID requires the Closing Disclosure (H-25).
Which page of the Closing Disclosure is most directly focused on calculating “Cash to Close” and summarizing the borrower’s and seller’s transactions?
Page 3 covers Cash to Close and the Summaries of Transactions.