16.2 Appraising Market Value
16.2 Appraising Market Value
Market value is an opinion of what a typical buyer and seller would agree to under normal conditions. In this topic, you’ll learn the conditions required for market value, how an appraisal differs from a broker’s opinion of value, common uses of appraisals, basic living area measurement guidelines, and the steps in the appraisal process.
Market Value (What It Means)
Market value is an opinion of the price that a willing buyer and willing seller would probably agree on for a property at a given time under normal conditions.
Market value assumes the following conditions are present:
- The transaction is a cash transaction (or cash-equivalent terms)
- The property is exposed on the open market for a reasonable time
- Buyer and seller have full information about market conditions and potential uses
- There is no abnormal pressure on either party
- Buyer and seller are unrelated (an arm’s-length transaction)
- Title is marketable and conveyable by the seller
- The price reflects normal consideration (no hidden financing deals, concessions, credits, services, fees, etc.)
Market Value vs. Market Price
Market price is what the property actually sells for. It should match market value if all market value conditions are present, but it may differ if the sale includes unusual pressure, special financing, concessions, or other non-typical terms.
The Appraisal and Its Uses
An appraisal is an opinion of value supported by data and performed by a professional, disinterested third party. Appraisers are regulated by state laws and bound to professional standards.
Broker’s Opinion of Value (How It Differs)
A broker’s opinion of value may resemble an appraisal, but it is not necessarily performed by a disinterested third party, is generally less comprehensive, and is not regulated or required to follow appraisal standards.
Common Uses of Appraisals
- Mortgage lending and underwriting decisions
- Setting selling prices and rental rates
- Determining insurance coverage levels
- Establishing investment value and collateral value
- Government and agency decision-making
Measuring Living Area (GLA Basics)
Living area is a major driver of residential value. Standards vary by area, but ANSI and Fannie Mae provide widely used national guidelines for measuring gross living area (GLA).
- Above grade: GLA is based on rooms above ground level, measured from exterior walls (includes stairwells; excludes open areas).
- Below grade: areas one foot or more below ground are counted as basement area, not 100% GLA.
- Ceiling height: minimum 7 feet; sloped ceilings require at least 50% of the area at 7 feet or more.
- Finished space: must be finished (floor covering + ceiling). Seasonal porches are excluded.
- Heated & attached: countable living area must be heated and attached to the main house.
- Attics/basements/garages: may not count as 100% GLA depending on finish/heat/local standards.
- Stairs/closets: generally count in GLA.
Steps in the Appraisal Process
Appraisers follow a systematic procedure to collect, organize, and analyze data and produce a supported opinion of value.
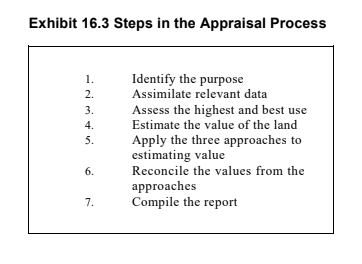
What those steps look like in plain English
- Identify the purpose: define the problem, property, interest, value type, and effective date.
- Assimilate relevant data: inspect property + gather market, tax, title, cost, and neighborhood data.
- Assess highest and best use: determine the most profitable use (may differ from current use).
- Estimate land value: typically using sales comparison on land-only comparables.
- Apply the three approaches: sales comparison, cost, and income (as appropriate).
- Reconcile: weigh the approaches and data quality to reach a final value opinion.
- Compile the report: deliver results in the requested format (form or narrative).
What’s It Worth?
Choose the best answer for each question, then select Check Answers.
Which condition is required for market value (as defined in this chapter)?
Reasonable open-market exposure is one of the conditions for market value.
In the appraisal process, adjustments are typically made after the appraiser:
The appraiser defines the purpose and gathers/organizes data before applying approaches and making comparisons/adjustments.