20.1 Fair Housing Laws
- Step 1: Memorize the protected classes and the big “don’ts” (steering, blockbusting, redlining, discriminatory ads).
- Step 2: Learn the key laws in order: 1866 → 1968 (Title VIII) → 1988 amendments → ADA.
- Step 3: Focus on real-world risk: clients can discriminate too—and agents can be liable if they participate.
- Read: Chapter 20 section on Fair Housing Laws
- Study aid: Exhibit 20.1 (Equal Opportunity in Housing Poster)
Fair housing laws (also called equal opportunity housing laws) exist to give all people an equal opportunity to buy, sell, rent,
or finance housing without discrimination—as long as they can afford it and meet legitimate requirements.
Federal law sets the national baseline, and many states have their own fair housing laws that generally mirror federal rules, sometimes with
additional protected classes or different procedures.
The Fair Housing Act prohibits discrimination in housing based on:
race, color, religion, sex, national origin, familial status, and disability.
The Act does not automatically override local zoning laws, but it does apply to municipalities and other local government entities.
That means zoning or land-use decisions cannot be used to exclude or discriminate against protected persons (including individuals with disabilities).
- Civil Rights Act of 1866: prohibits discrimination in housing based on race (selling, renting, inheriting, conveying).
- Executive Order 11063 (1962): prevents discrimination in residential properties financed by FHA and VA loans.
- Civil Rights Act of 1968 — Title VIII (Fair Housing Act): prohibits discrimination based on race, color, religion, national origin
(and later expanded). - Fair Housing Amendments Act of 1988: strengthened protections, including protections related to families with children and
persons with disabilities (and reinforced sex discrimination protections). - Americans with Disabilities Act (ADA): a broad civil rights law covering disability discrimination in public life; in real estate,
Titles I (employment) and III (public accommodations) are commonly encountered.
even when Fair Housing Act exemptions might otherwise apply.
- Discriminatory misrepresentation: hiding availability, changing terms, or claiming a property isn’t available to discriminate.
- Discriminatory advertising: wording or targeting that restricts availability to certain groups.
- Unequal services: providing different quality/level of service based on protected class.
- Steering: channeling buyers toward/away from neighborhoods using subjective descriptions to influence choices.
- Blockbusting: inducing owners to sell by suggesting demographic change will reduce values.
- Restricting MLS participation: limiting access based on protected classes.
- Redlining: refusing loans in certain areas regardless of applicant qualifications.
The Fair Housing Act allows limited exemptions in specific circumstances, such as:
- Privately owned single-family home (no broker used, no discriminatory advertising, and certain conditions met)
- Owner-occupied 1–4 unit building (no discriminatory advertising)
- Private club facilities leased non-commercially to members
- Religious organization facilities leased non-commercially to members (membership requirements not discriminatory)
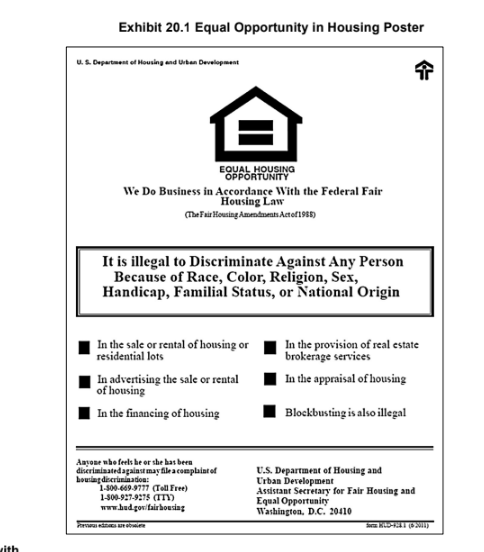
HUD requires brokers to display the Equal Opportunity in Housing poster. Failure to display it may be construed as discrimination.
Fair housing laws apply to sellers and landlords as well as agents (except where a lawful exemption applies).
If an agent participates in a client’s discriminatory act, the agent can be equally liable.
- Refusing a full-price offer for a discriminatory reason can create liability.
- Removing a property from the market to avoid a protected buyer/tenant is risky.
- Best practice: avoid complicity and withdraw if client discrimination occurs.
(generally within 2 years). Courts may award damages, injunctions, and civil penalties.
- Equal Credit Opportunity Act (ECOA): lenders must be fair in credit decisions and cannot discriminate based on
race, color, religion, national origin, sex, marital status, or age. Lenders must provide reasons for credit denial. - Home Mortgage Disclosure Act (HMDA): reporting designed to discourage discriminatory geographic lending patterns (helps combat redlining).
The Americans with Disabilities Act (ADA) prohibits discrimination against individuals with disabilities in many areas of public life.
In real estate practice, you’re most likely to encounter Titles I (employment) and III (public accommodations).
- Title I: applies to employers with 15+ employees and requires reasonable accommodations.
- Title III: requires accessible public accommodations and commercial facilities; barrier removal when “readily achievable.”
Licensees should explain general concepts but refer clients to qualified legal counsel for ADA compliance questions.
Fair Housing for All
Choose the best answer, then select Check Answers.
Which action is an example of illegal “steering”?
Steering is channeling buyers toward or away from certain areas using